
Last updated: July 2026. Pricing verified July 2026 — flat fee companies change plans often. Confirm current terms at checkout and in your signed listing agreement before relying on any figure below.
The "$99 Listing" That Costs $4,000 to Close
You paid $99 to get on the MLS. Felt like a win. Then the ALTA settlement statement lands, and there's a new line in your debit column — a "closing compliance fee," a "transaction fee," a percentage you don't remember agreeing to. On a Tennessee home near the state's median, that one line can run from a few hundred dollars to well over four thousand.
That's the gap this article closes. We're comparing the real cost to close three popular limited-service options — Houzeo, Brokerless, and ResultsMLS — on one benchmark: a $380,000 Tennessee home. Not sticker prices. Total dollars that leave your proceeds.
One disclosure up front: ResultsMLS publishes this article and is one of the three companies compared. We hold our own pricing to the exact same math, the same capture dates, and the same citations as the others. No softening. If our optional fees cost you money, you'll see them in the same column as everyone else's.
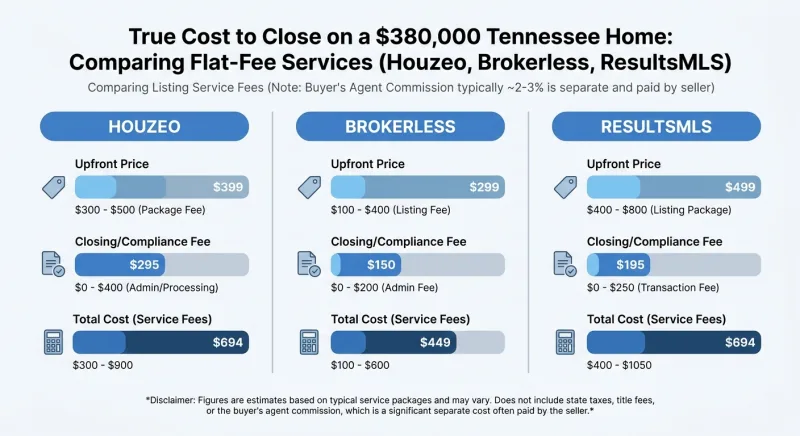
Houzeo vs Brokerless vs ResultsMLS: True Cost to Close on a $380,000 TN Home
Short answer: Houzeo's mid-tier plans carry the largest conditional closing cost — a percentage-based compliance fee (roughly 0.5%–1.25%) with a stated minimum — which on a $380,000 home can add roughly $999 to $4,750 at closing on top of the upfront price. Brokerless advertises no closing fee but may route a partner-broker transaction fee. ResultsMLS keeps its only percentage fee (0.25%) optional and disclosed upfront.
| Houzeo | Brokerless | ResultsMLS | |
|---|---|---|---|
| Upfront listing fee | $449–$499 (Silver/Gold/Platinum) | ~$99 base | $99 (or flat $399 Agent Support) |
| Closing / compliance fee | 0.5%–1.25%, $999 minimum on paid tiers | $0 advertised; possible partner-broker transaction fee | Optional 0.25% compliance fee |
| Compliance fee on $380K | ~$1,900–$4,750 (min $999) | Varies by partner broker | ~$950 (only if selected) |
| Est. all-in at $380K | ~$2,349–$5,249 | ~$99–$1,000+ depending on broker terms | ~$99–$1,049 depending on options |
How we calculated this: upfront price + the greater of the percentage fee or the stated minimum, applied to a $380,000 benchmark. Pricing captured July 2026 from each company's public pricing page and listing agreement. Verify at checkout before relying on these numbers.
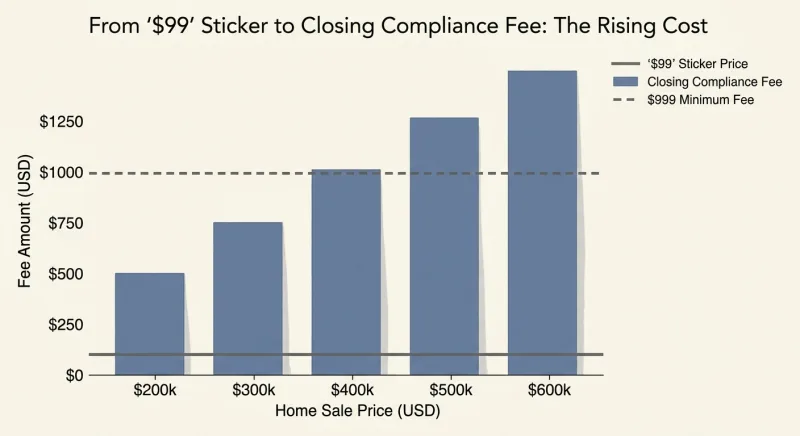
How a "Flat" Sticker Price Becomes a Percentage
A flat listing fee is real — you pay it once to get onto the MLS. The confusion starts when a company attaches a second charge that isn't flat at all. It's a percentage of your sale price, and it comes due at closing. By then you've signed, found a buyer, and the money comes straight out of your proceeds.
The mechanics are simple. A 1% fee on a $200,000 home is $2,000. The same 1% on a $600,000 home is $6,000 — same plan, same checkout screen, three times the cost.
Two things make this easy to miss:
- The fee lives in a listing addendum, not on the headline pricing card.
- It appears on the settlement statement weeks later, not at signup.
A stated minimum makes it worse at the low end. A "$999 minimum" means even a modest sale pays at least $999. The fee is engineered so you pay the greater of the two — you never win that coin flip.
When you compare plans, ignore the number on the button. Ask one question: what hits the debit column at closing?
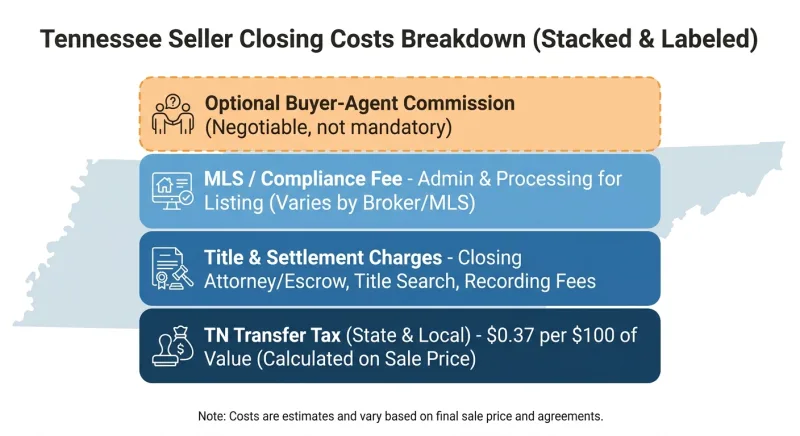
Where These Fees Appear: The ALTA Settlement Statement
Every Tennessee closing produces a settlement statement — commonly in ALTA format — itemizing every dollar in and out. The seller has a credits column (your sale price) and a debit column (everything subtracted from proceeds).
Flat fee compliance fees land in that debit column. So do:
- State transfer tax — $0.37 per $100 of value under T.C.A. § 67-4-409. On $380,000, about $1,406.
- Title and settlement fees — paid to the closing company.
- Any agreed buyer-agent commission — optional, but common if a buyer brings an agent.
The listing company's fee sits alongside those line items — which is exactly why it's easy to overlook at signup. You're looking at a $99 checkout total, not a settlement statement that won't exist until you're under contract. Read the addendum before you need the statement to explain it.
Why a Percentage Fee Scales Against You
A flat upfront price is fixed. A percentage closing fee is a variable cost tied to the one number that keeps climbing in Tennessee — your sale price.
On a $380,000 home, a 1.25% closing fee equals $4,750. A 0.5% fee equals $1,900. A 0.25% fee equals $950. Sell a $600,000 Brentwood home and that same 1.25% is $7,500. You did nothing different. The house just cost more.
The Break-Even Price Nobody Calculates
Break-even sale price = (Plan B upfront − Plan A upfront) ÷ Plan A's closing-fee percentage
Say Plan A charges $99 upfront plus a 0.5% closing fee, and Plan B charges a flat $399 with no closing fee. The upfront difference is $300. Divide by 0.005 and you get $60,000. Above a $60,000 sale price — essentially every Tennessee home — Plan B's flat structure wins. The "cheaper" $99 sticker loses the moment your home is worth more than a used truck.
Edge Cases That Break the Standard Comparison
The Price-Reduction and Re-List Trap
Percentage fees are usually calculated on final contract price. But if a contingent deal falls through and you re-list, check whether the compliance-fee clause resets, carries over, or re-triggers on the second contract. Some agreements bill the fee per executed contract, not per closed sale.
Seller Concessions
Watch how the fee base is defined. If the clause reads "percentage of gross sales price," a concession toward buyer closing costs won't reduce your fee — you pay the percentage on the full number. A clause reading "percentage of net proceeds" behaves differently. Two words in an addendum, hundreds of dollars apart.
Cancellation Before Close
Some agreements include a minimum earned fee or an administrative cancellation charge that survives termination. If the agreement is silent on cancellation, that silence favors the broker.
iBuyer and Cash-Investor Offers
If you accept a cash offer with no buyer's agent, the compliance fee often still applies — it's triggered by closing, not by procuring cause. Said plainly: if you already have a cash buyer in hand, the lowest-total-cost route is the plan with no percentage trigger at all — even if that isn't ResultsMLS. Fair is fair.
Match the Fee Structure to Your Deal
Stop asking "which company is cheapest?" Ask "which fee structure fits the sale I'm actually going to have?"
Profile 1 — High-value home ($600K+, Williamson/Davidson County). A percentage closing fee is your enemy. At 1.25%, a $650,000 Brentwood sale costs $8,125 in compliance fees alone. Prioritize plans that cap or eliminate the percentage.
Profile 2 — Median home (~$380K, Nashville metro). Run your break-even number. If you want hosting and full syndication, weigh the all-in cost — not the headline price.
Profile 3 — Lower-priced or rural home ($150K–$250K). The minimum fee dominates. A $999 floor on a $180,000 home is an effective 0.55% — higher than the advertised 0.5%. Minimums punish lower-priced sellers hardest.
Profile 4 — Fee-allergic seller with a buyer already lined up. Honest caveat against our own interest: if MLS exposure matters little and you've got a buyer, the cheapest route may be a bare-bones flat listing — or no MLS at all.
The Three Clauses to Read Before You Sign
- The fee-calculation base — gross sales price vs. net proceeds vs. list price.
- The minimum-fee floor — the dollar amount and whether it's waivable.
- The termination clause — cancellation charges, re-list triggers, minimum earned fees.
If any of the three is vague, get it in writing before signing the addendum.
How the Fee Stacks With Tennessee's Statutory Closing Costs
The state transfer tax under T.C.A. § 67-4-409 is $0.37 per $100 — roughly $1,406 on a $380,000 sale. That's fixed; no plan changes it. The one genuinely variable line the flat-fee company controls is its own compliance fee.
The transfer tax is the law. The compliance fee is a choice.
Disclosure Obligations Don't Change With Fee Structure
Tennessee's Residential Property Disclosure Act (T.C.A. § 66-5-201 et seq.) and TREC advertising rules still apply to every limited-service listing. A cheaper plan doesn't reduce your disclosure liability. Any company implying a higher tier "handles compliance for you" is selling convenience, not legal cover. The seller signs the disclosure. The seller owns it.
Watch the Partner-Broker Line
Some low-sticker plans route your listing through a partner broker that carries a separate transaction fee the headline price never mentions. The listing company's $99 can be genuinely flat while the broker's fee is a second, independent line item. Ask directly: "Is there any fee owed to a broker at closing that isn't on this page?" Get the answer in writing.
Watch What Renews
Optional add-ons — premium hosting, extended photo packages, "enhanced syndication" — sometimes bill monthly. If your home sits on RealTracs for five months, a $99/month add-on quietly becomes $495. List every conditional charge, including ones that renew.
When the Cheapest Plan Isn't Flat Fee MLS At All
If you're genuinely fee-allergic and selling in a hot micro-market where you already have a buyer, even the cheapest flat fee MLS plan may be more than you need. A true FSBO with no MLS listing costs nothing but time and a yard sign — you lose the RealTracs/MAAR/East Tennessee REALTORS/GCAR syndication that puts your home in front of every buyer's agent in the region. For most sellers that exposure is worth far more than it costs. For a few, it isn't.
Flat fee MLS wins when MLS exposure matters and you want to avoid a 2.5%–3% listing-side commission. It loses when exposure doesn't matter and any fee is one too many.
Publisher disclosure: ResultsMLS is both the publisher of this comparison and one of the companies compared. We've held our own pricing to the identical math and citation standard — because a fee breakdown only helps you if it's honest about everyone in it.
Frequently Asked Questions
Which flat fee MLS plan has the most hidden closing fees in Tennessee?
Houzeo's upper tiers carry the largest back-end exposure, charging a 0.5%–1.25% closing compliance fee with a $999 minimum. On a $380,000 home, that single line can run from $999 to roughly $4,750. Brokerless advertises zero closing fee but may route you through a partner broker that collects a transaction fee; ResultsMLS applies an optional 0.25% compliance fee only if you select that plan.
How much is the closing compliance fee in Tennessee flat fee MLS plans?
Compliance fees typically range from 0.25% to 1.25% of the sale price, or a flat minimum often near $999. On a $380,000 home, 0.25% equals $950 and 1.25% equals $4,750 — which is why reading the listing addendum matters more than comparing upfront prices.
Is the $0.37 transfer tax a hidden fee or a standard Tennessee closing cost?
It's a standard state cost, not a company fee. Under T.C.A. § 67-4-409, Tennessee charges $0.37 per $100 of the sale price — about $1,406 on a $380,000 home — and it applies no matter which flat fee company you use.
Do I still owe a buyer's agent commission if I use flat fee MLS?
Possibly. Flat fee MLS only covers your listing side; if the buyer brings an agent, you'll usually negotiate a commission (commonly 2%–3%) that appears in your debit column on the ALTA settlement statement.
Which MLS will my Tennessee home actually appear on?
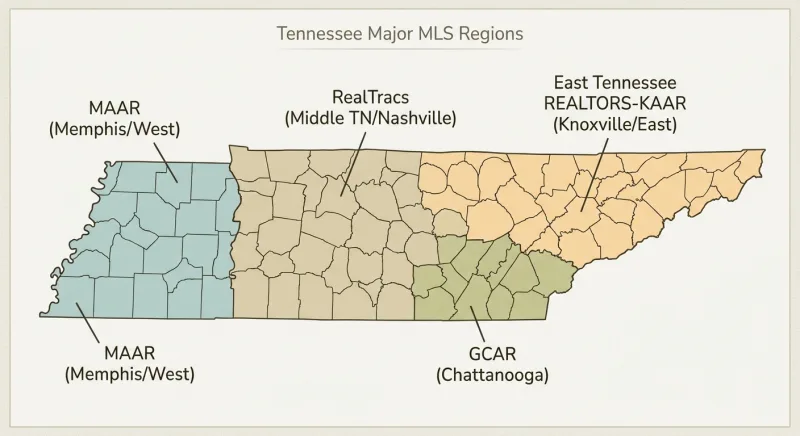
It depends on your region. RealTracs covers Middle Tennessee and Nashville, MAAR covers Memphis and West Tennessee, East Tennessee REALTORS (formerly KAAR) covers Knoxville and the east, and GCAR covers Chattanooga. Confirm your property's local board before paying.
Is flat fee MLS worth it in Tennessee if I want to avoid all fees?
For most sellers who want MLS exposure, yes — even with a compliance fee, total cost usually beats a full listing commission. But if you're truly fee-allergic and MLS reach matters less, a pure FSBO route can cost less.
The Bottom Line
The gap between a "$99 listing" and your actual closing-table total is where Tennessee flat fee MLS sellers get caught. Compliance fees that scale with your sale price, hosting add-ons, partner-broker transaction fees, and the buyer-agent commission all land in the same place: the debit column of your ALTA settlement statement.
Do three things before you sign. Pull the listing agreement and addendum — not the marketing page — and find the exact fee-trigger language. Run your own number at your home's actual price; at $380,000, a 1.25% compliance fee equals $4,750, while 0.25% equals $950. Confirm which MLS board actually serves your city.
Read the fine print once, and the closing table holds no surprises.
Last updated: July 2026. Pricing verified July 2026 — confirm current terms directly with each company before relying on these figures.